Introduction
Can a Singaporean buy a house in the United States without becoming an American citizen or obtaining a green card?
Yes. Singaporean citizens can generally purchase residential property in the United States without US citizenship, a green card, or a US visa.
Foreign buyers can purchase property for personal use, vacation purposes, or investment, subject to applicable federal, state, and local laws.
However, buying American real estate as a foreign national involves more than choosing a house and transferring money.
Singaporean buyers need to understand mortgage eligibility, international transfers, property taxes, rental income, FIRPTA withholding, estate tax, and the legal structure used to hold the property.
Some states also have restrictions affecting certain foreign individuals and entities.
This guide explains how Singaporeans can buy property in the USA in 2026, including the complete purchasing process, financing options, tax obligations, ownership structures, and important costs.
Whether you want a vacation home in Florida, an investment property in Texas, or a residential property for future use, this guide will help you understand the process before making a financial commitment.
1. Can Singaporeans Buy Property in the USA?
Yes. US federal law generally does not require a foreign buyer to be a US citizen or permanent resident to purchase ordinary residential property.
Singaporean citizens can generally purchase:
- Single-family houses
- Condominiums
- Townhouses
- Vacation homes
- Residential investment properties
A foreign buyer may generally own eligible property in their personal name or through an appropriate legal entity.
However, the rules depend on the property's location and the buyer's circumstances.
Certain states restrict property ownership by individuals or entities connected to designated foreign countries.
These restrictions may apply to agricultural land, properties near military installations, critical infrastructure, or other specified locations.
Therefore, buyers should check the applicable state law before making an offer.
Do Singaporeans Need a US Visa to Buy Property?
No. A US visa is generally not required simply to purchase residential property.
You may be able to complete the transaction while living in Singapore.
However, property ownership does not provide immigration benefits.
Buying a house in the USA does not automatically give you:
- A US visa
- A green card
- US citizenship
- Permission to work in America
- Permanent residency
If you want to visit, live, or work in the United States, you must separately meet the relevant immigration requirements.
Can Singaporeans Buy Property Remotely?
Yes. Many US property transactions can be completed remotely.
Depending on the lender, title company, state law, and transaction documents, remote buyers may be able to use:
- Electronic signatures
- Remote online notarization
- A properly executed power of attorney
- International notarization or authentication procedures
Some transactions still require original documents or specific signing procedures.
Before purchasing, confirm the closing requirements with your US attorney, lender, and title company.
2. US Foreign Ownership Restrictions: What Singaporeans Should Know
Foreign ownership restrictions are an important part of buying property in the United States.
The US does not have one universal rule that applies identically to every foreign buyer and every property.
Some states have introduced restrictions affecting people connected to designated countries of concern.
Florida Foreign Ownership Rules
Florida's SB 264 restricts certain foreign principals connected to designated countries of concern.
The law includes restrictions affecting agricultural land and certain properties near military installations or critical infrastructure.
It also establishes broader restrictions for specified individuals and entities connected to China.
The designated countries under the relevant provisions include China, Russia, Iran, North Korea, Cuba, Venezuela's Maduro regime, and Syria.
Singapore is not included in Florida's listed countries of concern under these provisions.
Therefore, an ordinary Singaporean citizen who is not otherwise covered by a restricted category is generally not prohibited from purchasing residential property solely because they are Singaporean.
However, buyers should still check the property's location, ownership structure, and applicable legal requirements.
Florida's foreign ownership laws have also faced legal challenges. Their application and legal status should be checked before closing.
Texas Foreign Ownership Rules
Texas also has foreign ownership restrictions.
SB 17 establishes restrictions affecting certain individuals and entities associated with designated countries.
The law includes China, Russia, Iran, and North Korea, along with other countries covered under its provisions.
Singapore is not included in the listed countries under the law's principal country-based restrictions.
However, the law's application depends on the buyer's legal status, ownership structure, and the specific property.
A Singaporean buyer should not assume that every foreign ownership restriction applies to them, but should also not assume that every transaction is automatically exempt.
What About California?
California does not have a general citizenship-based prohibition that automatically prevents an ordinary Singaporean individual from buying residential property.
However, buyers should still check the property's location, applicable agricultural-land rules, local requirements, and any restrictions relevant to their ownership structure.
The main considerations for many Singaporean residential buyers are financing, taxes, property costs, and compliance with applicable laws.
Important: State foreign ownership laws can change and may be challenged in court. Confirm the current rules with a qualified real estate attorney before purchasing.
Official resources:
- Florida Senate: https://www.flsenate.gov/Committees/billsummaries/2023/html/264
- Texas SB 17: https://capitol.texas.gov/tlodocs/89R/billtext/html/SB00017F.htm
- Congressional Research Service: https://crsreports.congress.gov/
3. Cash Purchase vs. Mortgage: Which Is Better for Singaporeans?
Singaporean buyers generally have two main ways to purchase US property.
Option A: Buying Property With Cash
A cash purchase is often the simplest option for a foreign buyer who already has sufficient funds.
You do not need to qualify for a mortgage or meet a lender's credit requirements.
You can generally transfer the purchase funds from Singapore to the US closing or escrow account.
However, the title company may still request identity verification, source-of-funds documentation, and other information.
Advantages of a cash purchase:
- No mortgage approval process
- No lender-required credit history
- No mortgage interest
- Potentially simpler financing arrangements
- Greater flexibility when making an offer
A cash purchase does not eliminate property taxes, insurance, maintenance, HOA fees, or US tax obligations.
You should also verify the closing company's wire instructions independently before sending money.
Option B: Getting a US Mortgage as a Singaporean
Foreign nationals may qualify for mortgage programs offered by lenders that work with international borrowers.
These programs are commonly described as:
- Foreign National Mortgage
- Nonresident Mortgage
- International Borrower Loan
- Portfolio Mortgage
- Certain Non-QM Mortgage Programs
Not every US bank offers these products.
Requirements depend on the lender, property type, loan amount, buyer's residency, income, and financial profile.
Foreign National Mortgage Requirements
| Requirement | What to Expect |
|---|---|
| Down payment | Often around 25%–40%, depending on lender |
| Passport | Usually required |
| US credit history | Some programs do not require established US credit |
| Singapore income | May be accepted with supporting documents |
| Bank statements | Singapore and other relevant accounts may be requested |
| Tax documents | Singapore tax assessments may be requested |
| Employment records | Payslips, employment letter, or business documents |
| Property appraisal | Usually required by the lender |
| Financial reserves | Additional funds may be required |
These are general examples, not guaranteed requirements.
A lender may require a larger down payment, additional reserves, translated documents, or a different loan structure.
Can Singapore Credit History Be Used?
Possibly.
Some foreign-national mortgage programs accept international credit reports, overseas credit references, or alternative financial documentation.
However, Singapore credit history is not automatically accepted by every US lender.
A lender may instead review:
- Singapore bank statements
- Employment and income history
- International credit references
- Existing loan obligations
- Available assets
- Previous mortgage payment records
Ask the lender whether it accepts Singapore credit documents before paying for an application or credit report.
Are Foreign National Mortgage Rates Higher?
They can be.
Foreign-national mortgage programs may have higher interest rates, additional fees, or stricter underwriting requirements than conventional US mortgages.
The difference depends on the lender and loan program.
Do not assume that every foreign buyer will pay exactly 1%–2% more interest.
Compare written loan estimates, including the annual percentage rate, fees, down payment, reserve requirements, and repayment terms.
4. Documents Singaporeans Need to Buy Property in the USA
The required documents depend on whether you are buying with cash or financing the property.
Cash Purchase Documents
A foreign buyer may need:
- Valid Singapore passport
- Proof of residential address
- Singapore bank statements
- Proof of available funds
- Source-of-funds documentation
- US tax identification information, if applicable
- Purchase agreement
- Ownership and closing documents
The title company may request additional information to satisfy identity verification and applicable compliance requirements.
Mortgage Documents
Mortgage applicants may need:
- Passport
- Singapore employment letter
- Recent payslips
- Singapore bank statements
- IRAS tax assessments
- International credit report or reference
- Existing loan statements
- Down payment documentation
- Proof of financial reserves
- Property purchase agreement
Self-employed buyers may need business financial statements, company registration documents, business bank statements, and additional income evidence.
Some lenders require documents to be translated into English or certified.
5. Do Singaporeans Need an ITIN to Buy Property?
An Individual Taxpayer Identification Number (ITIN) is a US tax identification number issued by the Internal Revenue Service.
It is intended for eligible individuals who need a US taxpayer identification number but are not eligible for a Social Security number.
An ITIN is not universally required before purchasing residential property in the USA.
A cash buyer may be able to complete a purchase without obtaining an ITIN beforehand.
However, an ITIN may become necessary when the foreign owner has US tax filing obligations.
For example, a nonresident foreign owner may need to file a US tax return because of rental income or a taxable property sale.
How to Apply for an ITIN
The IRS uses Form W-7 for ITIN applications.
Depending on the circumstances, applicants may need:
- A completed Form W-7
- Valid identity documents
- Supporting documentation explaining the tax-related reason for applying
- A US tax return, when required by the application procedure
Some applicants qualify for exceptions to the normal tax-return submission requirement.
The IRS also provides procedures involving authorized acceptance agents and other approved document verification methods.
Before applying, review the current IRS instructions.
Official resource:
https://www.irs.gov/individuals/individual-taxpayer-identification-number
An ITIN does not provide immigration status, employment authorization, or permission to live in the United States.
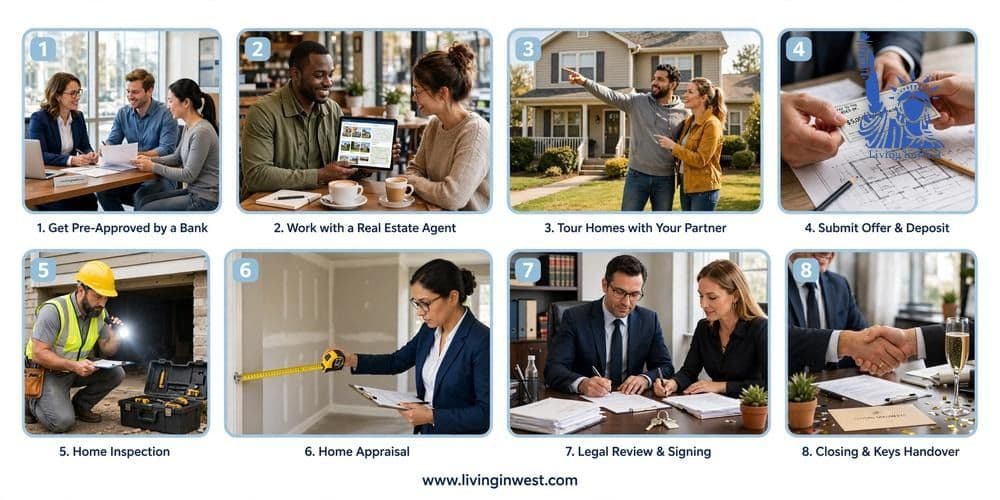
6. Step-by-Step Process: Buying Property in the USA From Singapore
The following process explains how a Singaporean buyer can purchase US property while living overseas.
Step 1: Decide Your Property Budget
Start by calculating how much you can afford.
Your budget should include more than the property's purchase price.
Consider:
- Down payment
- Closing costs
- Mortgage payments
- Property taxes
- Homeowners insurance
- HOA fees
- Maintenance
- Property management
- Currency exchange costs
For an investment property, estimate rental income and operating expenses before making an offer.
Do not assume a property will generate positive cash flow simply because its purchase price appears affordable.
Step 2: Choose a US State and City
Research the state and city where you want to buy.
Consider:
- Property prices
- Rental demand
- Local employment
- Property taxes
- Insurance costs
- HOA restrictions
- Local landlord regulations
- Foreign ownership restrictions
A property in a city with a lower purchase price may still have high insurance, maintenance, or property tax expenses.
Step 3: Find a US Real Estate Agent
Choose a real estate agent who has experience working with international buyers.
The agent can help you:
- Search for properties
- Arrange virtual property tours
- Review local market conditions
- Prepare an offer
- Coordinate inspections
- Communicate with the seller
Confirm how the agent is compensated and who represents your interests.
For important legal questions, use a qualified US real estate attorney.
Step 4: Arrange Mortgage Preapproval
If you need financing, contact lenders that work with foreign nationals.
Ask about:
- Minimum down payment
- Interest rate
- Loan term
- Eligible property types
- Required income documents
- Singapore credit history
- US tax identification requirements
- Closing costs
- Reserve requirements
Obtain written financing terms before making a serious offer.
A mortgage preapproval is not the same as final loan approval.
Step 5: Search for Properties
You can use US property websites to research available homes.
Examples include:
- Zillow
- Realtor.com
- Redfin
These websites can help you compare listings, property prices, locations, and estimated rental information.
However, listing details, property taxes, HOA fees, and rental estimates should be independently verified.
Arrange a professional property inspection before closing.
Step 6: Make an Offer
Once you select a property, your real estate agent can help prepare the offer.
The offer may include:
- Purchase price
- Earnest money deposit
- Financing contingency
- Inspection contingency
- Closing date
- Other negotiated conditions
Earnest money is a deposit demonstrating that the buyer intends to proceed.
The amount varies by market and transaction.
It is not universally fixed at 1%–3%.
The purchase agreement should explain when the deposit is refundable and when it may be forfeited.
Step 7: Complete Due Diligence
Before closing, review the property's legal and financial condition.
Important checks include:
- Property inspection
- Title search
- Existing liens
- Property tax records
- HOA documents
- Insurance availability
- Rental restrictions
- Local zoning
- Mortgage approval
For investment properties, verify whether the property can legally be rented under local rules and HOA restrictions.
Step 8: Complete the Closing
The closing process transfers ownership from the seller to the buyer.
The closing may involve:
- Title company
- Escrow agent
- Real estate attorney
- Mortgage lender
- Insurance provider
You will review and sign the required documents and transfer the purchase funds.
Remote closing options depend on the state, title company, lender, and document requirements.
A Singapore-based buyer may not need to travel to the United States if the transaction can be completed using an accepted remote signing procedure.
Step 9: Register and Manage Your Property
After closing:
- Confirm that the deed has been recorded
- Arrange property insurance
- Set up property tax payments
- Review HOA obligations
- Arrange maintenance
- Hire a property manager if necessary
If you intend to rent the property, understand the applicable landlord, tenant, and tax requirements.
7. Hidden Costs Singaporeans Should Understand
The purchase price is only one part of the total cost of owning US real estate.
1. Closing Costs
Closing costs may include:
- Title insurance
- Escrow fees
- Attorney fees
- Mortgage lender fees
- Appraisal fees
- Recording fees
- Prepaid insurance
- Property tax adjustments
Costs vary by state and transaction.
Request a detailed closing cost estimate before making an offer.
2. Property Taxes
US property taxes are generally assessed by local governments.
The amount depends on the property's assessed value, applicable tax rates, exemptions, and local rules.
Property taxes are not uniformly 1%–2% across the United States.
Some locations have relatively low effective property tax rates, while others have substantially higher rates.
Check the property's actual tax records instead of relying on a national estimate.
3. Homeowners Insurance
Insurance costs depend on:
- Property location
- Property value
- Construction type
- Coverage amount
- Claims history
- Weather and disaster risks
In some locations, particularly areas exposed to hurricanes, flooding, or wildfire, insurance may be expensive or difficult to obtain.
Obtain an insurance quote before closing.
4. HOA Fees
Condominiums, townhouses, and some residential communities charge homeowners association fees.
These fees may cover:
- Common-area maintenance
- Building management
- Shared facilities
- Landscaping
- Certain utilities
- Community insurance
Review the association's financial statements, rules, reserves, and possible special assessments.
5. Currency Exchange
Singaporean buyers transferring money to the USA must consider the SGD/USD exchange rate.
Exchange costs may include:
- Bank transfer fees
- Currency conversion margins
- Correspondent bank charges
- Receiving bank fees
Compare the total amount received in USD rather than only the advertised exchange rate.
8. US Rental Income Tax for Singaporean Property Owners
If a Singaporean nonresident owns US property and receives rental income, US tax rules may apply.
This is one of the most important sections for buyers purchasing property as an investment.
The 30% Gross Rental Income Rule
US-source rental income received by a nonresident alien is generally treated as fixed, determinable, annual, or periodic income (FDAP) when it is not effectively connected with a US trade or business.
Under the general rule, this income may be subject to 30% US federal tax on gross rental income, unless a lower treaty rate applies.
The gross-income approach generally does not allow deductions for property expenses.
This means the tax calculation can be very different from the calculation of rental profit.
For example, a property owner may receive rent but also pay:
- Mortgage interest
- Property management
- Repairs
- Insurance
- Property taxes
- Maintenance
Under the default gross-income treatment, those expenses generally do not reduce the taxable FDAP amount.
Example: $30,000 Annual Rental Income
Suppose a Singaporean nonresident receives $30,000 in gross annual rent from a US property.
Under the general 30% gross-income rule:
| Item | Amount |
|---|---|
| Gross rental income | $30,000 |
| Illustrative 30% tax | $9,000 |
| Rental income after this tax | $21,000 |
This example does not include other taxes, expenses, withholding adjustments, or any applicable exceptions.
The actual treatment depends on the owner's circumstances.
Can Foreign Owners Deduct Rental Expenses?
Potentially, yes.
A nonresident owner may elect to treat eligible US real property income as effectively connected with a US trade or business under the applicable tax rules.
This is commonly called the ECI election for real property income.
When the election applies, eligible rental income can generally be taxed on a net basis after allowable deductions.
Potential deductions may include:
- Property management
- Repairs
- Insurance
- Property taxes
- Eligible mortgage interest
- Depreciation
The resulting taxable income is generally subject to graduated federal income tax rates rather than the default 30% gross-income tax.
The owner must satisfy the applicable requirements and file the appropriate US tax return.
Which Form Does a Foreign Rental Property Owner File?
A nonresident individual with applicable US rental income generally files Form 1040-NR.
Depending on the tax treatment, rental income and expenses may be reported through the appropriate schedules.
The owner may also need to arrange appropriate withholding and provide tax documentation to the property manager or other relevant parties.
Important: Do not assume that hiring a property manager automatically makes the rental income effectively connected income.
The correct treatment should be reviewed with a CPA who handles US nonresident real estate taxation.
Official IRS resources:
9. Singapore–US Tax Treaty: What Property Buyers Should Know
Singapore and the United States do not have a comprehensive income tax treaty that generally provides treaty-based reductions for US real estate rental income.
The IRS's official income tax treaty list does not include Singapore as a treaty partner.
The IRS estate and gift tax treaty list also does not include Singapore.
Therefore, Singaporean buyers should not assume that they qualify for a treaty reduction in US rental income tax or US estate tax.
This matters because:
- The general 30% gross rental income rule may apply when the income is not effectively connected with a US trade or business.
- FIRPTA withholding rules may apply when selling US real property.
- US estate tax rules may apply to US-situated assets held at death.
Singapore tax treatment should also be reviewed separately.
A Singapore tax professional can help determine whether the income or gain has any Singapore tax consequences and whether foreign tax relief may be available under Singapore law.
Official resources:
- IRS income tax treaties: https://www.irs.gov/individuals/international-taxpayers/united-states-income-tax-treaties-a-to-z
- IRS estate and gift tax treaties: https://www.irs.gov/businesses/small-businesses-self-employed/estate-gift-tax-treaties-international
10. FIRPTA Tax When Selling US Property
FIRPTA stands for the Foreign Investment in Real Property Tax Act.
It generally requires withholding when a foreign person sells US real property.
The withholding is collected to help ensure that the seller's US tax obligations are addressed.
However, FIRPTA withholding is not necessarily the seller's final tax liability.
Standard FIRPTA Withholding
For many transactions, the standard withholding rate is 15% of the amount realized.
The amount realized is generally based on the sale price and certain other amounts included under the applicable tax rules.
It is not simply 15% of the seller's profit.
For example, a property may have:
- A $400,000 sale price
- A $250,000 original purchase price
- Selling expenses
- Mortgage payoff
The FIRPTA withholding calculation is not automatically based on the difference between the sale price and original purchase price.
FIRPTA Reduced Withholding for a Buyer Who Will Use the Property as a Residence
The withholding rules can be different when the buyer intends to use the property as a residence.
| Amount Realized | General FIRPTA Residence Rule |
|---|---|
| $300,000 or less | Potentially 0% withholding |
| More than $300,000 and up to $1 million | Generally 10% withholding |
| More than $1 million | Generally 15% withholding |
These reduced rates are conditional.
For the residence-related rules, the buyer must meet the applicable intention and use requirements.
Generally, one or more buyers must have definite plans to reside in the property for at least 50% of the number of days the property is used by any person during each of the first two 12-month periods following the transfer.
Vacant days are not counted in determining the number of days the property is used by any person.
A Singaporean buying a property purely for rental investment should not assume that the residence-related reduced withholding rules apply.
Can FIRPTA Withholding Be Reduced Further?
Yes, in certain circumstances.
A foreign seller may request a withholding certificate from the IRS.
The certificate may allow the buyer or closing agent to withhold a reduced amount based on the applicable tax calculation.
The application must meet the IRS requirements.
A withholding certificate is not automatic, and the seller should plan ahead because processing time can affect the closing.
Example: Foreign Seller With a $400,000 Property
Suppose a Singaporean nonresident sells a US property for $400,000.
If the standard 15% withholding applies:
| Item | Amount |
|---|---|
| Sale price | $400,000 |
| Illustrative FIRPTA withholding at 15% | $60,000 |
This $60,000 is withholding, not necessarily the final tax.
The seller's actual US tax liability may be lower or higher depending on the applicable rules, deductions, gain calculation, and other circumstances.
The seller may need to file a US tax return to calculate the final tax and claim a refund of excess withholding.
Official IRS resource:
https://www.irs.gov/individuals/international-taxpayers/firpta-withholding
11. US Estate Tax: A Major Issue for Foreign Property Owners
Estate tax is one of the most important considerations for Singaporeans who own US real estate.
For certain nonresident, non-US-citizen individuals, US estate tax rules apply to US-situated assets.
US real estate is generally considered a US-situated asset.
The $60,000 Estate Tax Filing Threshold
The IRS generally requires the executor of a nonresident, non-US-citizen estate to file Form 706-NA when the fair market value of the deceased person's US-situated assets exceeds $60,000, subject to applicable rules.
The filing calculation can also involve adjusted taxable gifts and other relevant amounts.
The $60,000 threshold is not the same as the much larger federal estate tax exclusion generally available to US citizens and residents.
It is an important threshold for foreign property owners.
Form 706-NA Deadline
The executor generally must file Form 706-NA within nine months after the date of death, unless an extension applies.
Estate tax payment is also generally due within the applicable nine-month period unless an extension or other relief applies.
The executor should obtain professional advice promptly.
Does a Foreign Owner Automatically Pay 40% Estate Tax?
No.
It would be incorrect to say that every foreign property owner automatically pays 40% tax on the entire property value.
The actual estate tax calculation depends on:
- The value of US-situated assets
- Applicable deductions
- Taxable estate calculation
- Available credits
- Ownership structure
- Estate tax treaty provisions, where applicable
- Other relevant circumstances
However, the risk can be substantial.
The federal estate tax rate schedule can reach 40%.
Example: A Foreign Owner With a $1 Million US Property
Suppose a Singaporean nonresident owns a US property worth $1 million at death.
The property may be included in the US-situated assets considered for estate tax purposes.
The estate may need to file Form 706-NA if the applicable filing threshold is exceeded.
For a simplified illustration, assume:
- The property is worth $1 million at death.
- There are no other US-situated assets.
- No deductions reduce the taxable estate.
- No treaty relief applies.
- The estate qualifies only for the applicable nonresident credit.
Under these assumptions, the US estate tax could be approximately $332,800 using the applicable estate tax calculation and credit.
This is an illustration, not a universal tax estimate.
The actual tax can change significantly depending on the estate's facts, deductions, ownership, liabilities, and available credits.
The important point is that a foreign owner may face substantial US estate tax exposure even when the property was purchased for personal use.
Can an LLC Avoid US Estate Tax?
Not automatically.
An LLC may provide liability separation or administrative benefits, but it should not be treated as a guaranteed estate tax solution.
The tax consequences of owning US real estate through a US LLC can depend on the entity's classification, ownership, applicable tax rules, and estate planning circumstances.
An LLC can also create additional reporting obligations.
A Singaporean buyer should obtain advice from a US estate planning attorney and a cross-border tax professional before selecting an ownership structure.
Official IRS resources:
- https://www.irs.gov/individuals/international-taxpayers/some-nonresidents-with-us-assets-must-file-estate-tax-returns
- https://www.irs.gov/businesses/small-businesses-self-employed/frequently-asked-questions-on-estate-taxes-for-nonresidents-not-citizens-of-the-united-states
- https://www.irs.gov/instructions/i706na
12. FinCEN Residential Real Estate Reporting Rule: October 2026 Update
Foreign buyers using an LLC or trust should understand the current status of the FinCEN Residential Real Estate Reporting Rule.
The rule was designed to require reporting of certain residential real estate transfers involving legal entities or trusts.
It was particularly relevant to certain non-financed transactions.
However, the rule's legal status changed in 2026.
What Happened on March 19, 2026?
On March 19, 2026, a federal district court in the Eastern District of Texas issued an order vacating the Residential Real Estate Rule.
FinCEN and the Department of Justice appealed the decision.
FinCEN's official FAQ, issued May 18, 2026, states that while the court order remains in force:
- Reporting persons are not currently required to file Real Estate Reports under the rule.
- Reporting persons are not subject to liability for failing to file while the order remains in force.
- If the order is overturned, covered transactions during the period of the order will not require retroactive filing under the FAQ.
What Does This Mean for Singaporean Buyers?
As of the October 26, 2026 article update, the official FinCEN guidance available for this article states that the rule remains vacated while the court order is in force and that the appeal is pending.
This is a time-sensitive legal issue.
Before closing, check the official FinCEN page for any new court decision, agency guidance, or reporting requirement.
The court ruling does not remove other requirements.
A buyer may still need to provide:
- Identity documents
- Source-of-funds information
- Bank statements
- Ownership information
- Tax identification details
- Documents requested by the title company or financial institution
The ruling does not remove all anti-money-laundering, banking, title, or tax compliance obligations.
Official FinCEN resources:
- Residential Real Estate FAQs: https://www.fincen.gov/rre-faqs
- Residential Real Estate Rule: https://www.fincen.gov/rre
- Reference Materials: https://www.fincen.gov/rre-reference-materials
13. Should Singaporeans Buy Property Through an LLC?
A US limited liability company (LLC) is a legal entity that may be used to hold property.
Some foreign investors consider an LLC for liability management, ownership administration, or investment organization.
However, an LLC is not automatically the best structure for every Singaporean buyer.
Advantages of an LLC
Depending on the circumstances, an LLC may provide:
- Separation between personal and business liabilities
- A structure for multiple investors
- Investment administration
- Potential privacy benefits, subject to disclosure requirements
- Flexibility in ownership arrangements
Disadvantages of an LLC
An LLC may also create:
- State registration fees
- Annual reporting requirements
- Additional accounting costs
- Tax filing obligations
- Mortgage restrictions
- Complicated cross-border tax treatment
Foreign-owned single-member LLCs may have additional IRS reporting requirements.
For example, certain foreign-owned disregarded entities must file Form 5472 with a pro forma Form 1120 when applicable reporting requirements are met.
Failure to comply can result in significant penalties.
Personal Name vs. LLC
| Ownership Method | Potential Advantages | Important Considerations |
|---|---|---|
| Personal name | Simpler ownership and administration | Estate tax and personal liability considerations |
| US LLC | Liability separation and investment organization | Tax, reporting, lender, and compliance costs |
| Other entity or trust | May suit specialized planning | Requires professional legal and tax advice |
There is no universal rule that personal ownership is always best for a first property.
The appropriate structure depends on the property, financing, liability concerns, estate planning, and tax consequences.
Speak with a US real estate attorney and cross-border tax professional before deciding.
14. Best US States for Singaporean Property Buyers in 2026
The best state depends on whether you want rental income, a vacation property, future personal use, or long-term investment.
Florida
Florida may appeal to buyers interested in:
- Vacation homes
- Residential rental properties
- Cities with tourism activity
- No general state individual income tax
Potential locations include Orlando and Tampa.
However, buyers should carefully review homeowners insurance, hurricane exposure, flood risk, property taxes, HOA fees, and local rental regulations.
Florida also has restrictions affecting certain foreign persons and entities.
Check the property's location and applicable state laws before purchasing.
Texas
Texas may appeal to investors interested in:
- Major employment centers
- Residential rental markets
- Cities with substantial population growth
- No general state individual income tax
Potential locations include Houston, Austin, and Dallas.
Texas property taxes can be substantial, and costs vary by county and school district.
Insurance, HOA fees, and local property regulations should also be considered.
Arizona
Arizona may be worth researching for buyers interested in residential property in cities such as Phoenix and Tucson.
Consider:
- Local housing prices
- Rental demand
- Water availability
- Insurance
- Property taxes
- Local regulations
Do not choose a property based solely on a low purchase price.
California
California may appeal to buyers interested in established housing markets, major employment centers, and international communities.
However, property prices, insurance, maintenance, and local regulations can make ownership expensive.
Buyers should also investigate any applicable restrictions affecting certain foreign purchasers.
How to Choose the Right State
Before choosing a state, compare:
- Property purchase price
- Expected rental income
- Property tax
- Insurance
- HOA fees
- Maintenance
- Local landlord rules
- Foreign ownership restrictions
A state with no general state income tax does not necessarily offer the lowest overall property ownership cost.
15. Example: Buying a $300,000 Property in the USA
Let's consider a hypothetical Singaporean buyer purchasing a property worth $300,000.
This example is for budgeting only. It is not a mortgage quote or a prediction of actual costs.
Example Mortgage Budget
| Item | Example Amount |
|---|---|
| Property price | $300,000 |
| Down payment at 30% | $90,000 |
| Mortgage amount | $210,000 |
| Illustrative closing costs at 3% | $9,000 |
| Initial purchase funds | $99,000 |
The buyer would need approximately $99,000 for the down payment and assumed closing costs.
This does not include additional reserves, insurance, property taxes, repairs, or other expenses.
Actual closing costs may be lower or higher than the example.
Cash Purchase Example
| Item | Example Amount |
|---|---|
| Property price | $300,000 |
| Assumed closing costs at 3% | $9,000 |
| Initial purchase funds | $309,000 |
A cash buyer would not have mortgage payments but would still need to pay ongoing ownership expenses.
Monthly Ownership Costs
Depending on the property, monthly costs may include:
- Mortgage payment
- Property tax
- Insurance
- HOA fees
- Maintenance
- Property management
For an investment property, calculate net rental income after these expenses.
Do not use gross rent as the expected profit.
16. Can Singaporeans Rent Out Their US Property?
Yes. Foreign owners can generally rent out eligible US residential property, subject to local laws and property restrictions.
However, rental ownership involves more than finding a tenant.
You should consider:
- Local landlord registration
- Rental permits
- HOA rental restrictions
- Tenant screening
- Lease agreements
- Property maintenance
- Insurance
- US tax filing
A property manager can help oversee the rental while you remain in Singapore.
Before buying, verify that the property is legally eligible for your intended rental strategy.
Short-term rentals may face different restrictions from long-term residential leases.
17. Important Mistakes Singaporeans Should Avoid
Mistake 1: Assuming Property Ownership Gives a Green Card
Buying residential property does not provide a US immigration pathway.
Property ownership and immigration eligibility are separate legal matters.
Mistake 2: Assuming Every Foreign Buyer Can Get a Mortgage
Mortgage approval depends on the lender and the buyer's financial profile.
A foreign-national mortgage is not guaranteed.
Mistake 3: Ignoring Property Taxes
Property tax can significantly affect annual ownership costs.
Check actual local tax records.
Mistake 4: Buying Without Checking Insurance
Some properties have high insurance costs or limited insurance availability.
Obtain an insurance quote before closing.
Mistake 5: Using an LLC Without Tax Advice
An LLC may provide useful legal or administrative benefits, but it can also create reporting and tax complications.
Choose the structure based on your circumstances.
Mistake 6: Assuming FIRPTA Is the Final Tax
FIRPTA withholding is not necessarily the final tax liability.
The seller may need to file a US tax return to calculate the actual tax.
Mistake 7: Ignoring Rental Income Tax
A foreign owner may face 30% gross rental income tax under the default FDAP rules when the income is not effectively connected with a US trade or business and no lower treaty rate applies.
Review the ECI election and applicable deductions before buying an investment property.
Mistake 8: Assuming the FinCEN Rule Is Permanently Cancelled
The Residential Real Estate Reporting Rule was vacated by a federal court in March 2026.
However, its legal status could change during the appeal.
Check the latest FinCEN guidance before closing.
Mistake 9: Transferring Money Without Verifying Instructions
International property transactions can involve wire fraud.
Verify the recipient's account details using a trusted phone number before sending funds.
18. Final Checklist for Singaporeans Buying Property in the USA
Before purchasing, confirm the following:
- Property location and applicable foreign ownership rules checked
- Purchase budget calculated
- Down payment available
- Mortgage preapproval obtained, if financing
- Passport and identity documents ready
- Singapore income and tax documents prepared
- Source of funds documented
- US real estate agent selected
- Attorney or title company selected
- Property inspection completed
- Property taxes reviewed
- Insurance quote obtained
- HOA restrictions reviewed
- Closing costs estimated
- US rental income tax requirements discussed
- FIRPTA withholding rules reviewed
- Estate tax implications reviewed
- Ownership structure discussed with professionals
- Rental management arranged, if required
- FinCEN reporting status checked before closing
Conclusion
Singaporeans can generally buy residential property in the United States without US citizenship, a green card, or a visa.
A cash purchase may be simpler for buyers who already have sufficient funds, while foreign-national mortgage programs can provide financing for eligible nonresident buyers.
The most important considerations are the property's location, financing requirements, total ownership costs, US tax obligations, and the legal structure used to hold the property.
Foreign buyers should pay particular attention to rental income taxation, FIRPTA withholding when selling, and the potential US estate tax exposure associated with US-situated assets.
The FinCEN Residential Real Estate Reporting Rule was vacated in March 2026, but its appeal and other compliance obligations should be monitored.
The best approach is to choose a property based on your financial goals and the complete cost of ownership—not simply the purchase price or the state's income tax rate.
Before purchasing, verify state-specific foreign ownership restrictions, obtain professional tax advice, and review the property carefully.
Frequently Asked Questions (FAQs)
1. Can a Singaporean buy a house in the USA without a green card?
Yes. US citizenship and a green card are generally not required to purchase residential property. However, state-specific restrictions may apply.
2. Can I buy US property while living in Singapore?
Yes. Many purchases can be completed remotely, subject to the lender, title company, state law, and closing requirements.
3. Do Singaporeans need an ITIN to buy property in the USA?
Not universally. An ITIN may be needed for certain US tax filing obligations, but it is not automatically required before every property purchase.
4. Can a Singaporean get a US mortgage?
Yes, some lenders offer foreign-national mortgage programs. Approval, down payment, interest rate, and documentation requirements vary.
5. How much down payment is required?
Some foreign-national mortgage programs require approximately 25%–40% down. The exact amount depends on the lender and property.
6. Do foreign property owners pay US taxes?
They may have US tax obligations related to rental income, property sales, and other applicable matters. Property taxes are also generally payable to local governments.
7. What is FIRPTA?
FIRPTA is a US tax law that generally requires withholding when foreign persons sell US real property. The withholding is not necessarily the seller's final tax.
8. Can FIRPTA withholding be reduced?
Yes. Certain residence-related transactions may qualify for reduced or eliminated withholding. A seller may also apply for an IRS withholding certificate when eligible.
9. What is the US estate tax threshold for foreign property owners?
For certain nonresident, non-US-citizen estates, the general filing threshold is $60,000 in US-situated assets, subject to applicable rules and adjustments.
10. Can buying property in the USA give me a green card?
No. Purchasing residential property does not automatically provide a visa, green card, or citizenship.
11. Can I buy property through an LLC?
Yes, an eligible LLC may hold property. However, the structure can involve additional tax, reporting, legal, and mortgage requirements.
12. Which US state is best for Singaporean property investors?
Florida, Texas, Arizona, and California may be worth researching, but the best choice depends on property prices, taxes, insurance, rental demand, local laws, and your investment goals.
Official Sources and Further Reading
IRS – ITIN
https://www.irs.gov/individuals/individual-taxpayer-identification-number
IRS – FIRPTA Withholding
https://www.irs.gov/individuals/international-taxpayers/firpta-withholding
IRS – Taxation of Nonresident Aliens
https://www.irs.gov/individuals/international-taxpayers/taxation-of-nonresident-aliens
IRS – Effectively Connected Income
https://www.irs.gov/individuals/international-taxpayers/effectively-connected-income-eci
IRS – US Income Tax Treaties
https://www.irs.gov/individuals/international-taxpayers/united-states-income-tax-treaties-a-to-z
IRS – Estate and Gift Tax Treaties
https://www.irs.gov/businesses/small-businesses-self-employed/estate-gift-tax-treaties-international
IRS – Estate Tax for Nonresident Property Owners
IRS – Form 706-NA Instructions
https://www.irs.gov/instructions/i706na
FinCEN – Residential Real Estate Reporting FAQs
https://www.fincen.gov/rre-faqs
FinCEN – Residential Real Estate Rule
Florida Senate – Foreign Ownership Legislation
https://www.flsenate.gov/Committees/billsummaries/2023/html/264
Texas SB 17
https://capitol.texas.gov/tlodocs/89R/billtext/html/SB00017F.htm
Disclaimer
This article is for general educational and informational purposes only. It is not legal, tax, mortgage, immigration, or investment advice.
US property laws, foreign ownership restrictions, mortgage requirements, tax rules, and closing procedures may change.
Consult a qualified US real estate attorney, mortgage professional, and tax advisor before purchasing property.
Article updated October 26, 2026. Verify current legal and tax requirements before making a transaction.
Editorial Team